
Most financial advisers charge a percentage of your wealth every year. A fixed-fee planner charges for the work they actually do. That distinction sounds small. It isn't.
Imagine hiring a solicitor to draft your will. You wouldn't expect the bill to be calculated as a percentage of your estate. A £3 million estate and a £500,000 estate might need the same document, the same legal expertise, the same hours of work. You'd pay for the service, not for how much you happen to own.
Nobody would accept anything else from a solicitor, an accountant, or an architect. Yet the financial advice industry has operated on a different logic for decades. The standard model takes a slice of your investments - typically around 1% per year - and that slice grows automatically as your portfolio grows. Your adviser earns more without doing more.
On a £500,000 portfolio, a 1% annual charge costs £5,000 a year. If the portfolio value stayed at £500,000, that would total £100,000 over twenty years in ongoing advice fees alone, excluding initial advice, implementation, platform and fund costs. This simple illustration assumes an unchanged fee rate and portfolio value, with no inflation adjustment; it is not a forecast. NextWealth's 2024 Financial Advice Business Benchmarks report found that total ongoing costs for advised UK investors now average 1.89% annually.
Fixed-fee financial planning offers an alternative. You pay a set amount, agreed before any work begins, based on what your situation actually requires. Not what your portfolio happens to be worth.
How fixed-fee planning works in practice
A fixed-fee planner assesses the complexity of your financial life and quotes a price in pounds. Someone consolidating two workplace pensions pays less than someone selling a business, restructuring a property portfolio, and planning for retirement abroad. The fee reflects the work. Nothing else.
At rockwealth, the process typically breaks into three stages:
Initial planning - a deep analysis of where you stand today, what you want your future to look like, and a detailed plan to bridge the gap. This is what we call the Financial MasterPlan.
Implementation - putting the recommendations into action. Restructuring pensions, building an investment portfolio, arranging tax-efficient wrappers.
Ongoing advice - the continuing relationship. Regular reviews, adjustments when your circumstances change, and direct access to your planner whenever you need it.
Each stage has a clear fee, quoted upfront. You know what you're paying before you commit to anything.
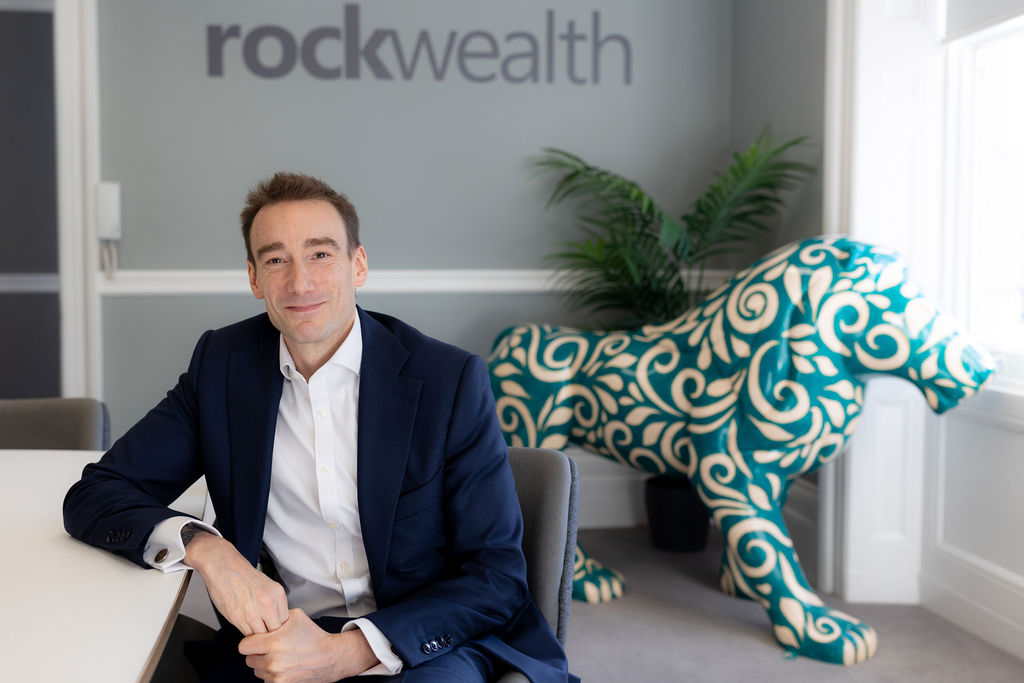
Robert Smith, financial planner at rockwealth Chiswick, explains the thinking: "My preferred approach - the fairer approach - is to treat every person as an individual. What level of work is involved in helping this client get to where they need to be, and what's a fair fee for that work? It's got to be fair for us as much as it is fair for the client. But it's about making sure nobody pays more than the value they receive."
The problem with percentage fees
Percentage-based charging creates an uncomfortable misalignment between your interests and your adviser's.
Consider two clients. One has £400,000 in investments. The other has £2 million. Both need the same advice: a pension drawdown strategy, a tax review, an annual check-in. At 1%, the first client pays £4,000 a year. The second pays £20,000. Five times the fee for the same work.
The wealthier client subsidises the business. The less wealthy client may be turned away entirely. NextWealth's 2024 data showed that 79% of UK advice firms now require a minimum of £100,000 in investable assets. One in five won't take clients with less than £200,000.
There's a deeper issue. When an adviser's income is tied to the size of your portfolio, they have a financial reason to keep your money invested with them - even when the best advice might be to pay off your mortgage, help your children onto the property ladder, or simply spend more freely in retirement. Most advisers wouldn't consciously steer you wrong. But the incentive structure nudges in one direction.
Fixed fees remove that tension entirely. Your planner earns the same regardless of what you do with your money. The only incentive is to give you the best possible advice, because that's what keeps you coming back and referring others.
rockwealth operates primarily on fixed fees for exactly this reason, though percentage-based charging is available where it genuinely works out better for the client. The principle isn't dogma. It's doing whatever serves you.
Better incentives lead to better outcomes
This isn't just about fairness. The way you pay for advice shapes the advice itself.
The single biggest drag on investment returns isn't fees, fund performance, or market conditions. It's investor behaviour. Morningstar's 2025 Mind the Gap study found that investors surrendered 1.22 percentage points annually over the decade to December 2024 through poorly timed decisions - buying when markets were high and selling when they fell. Over ten years, that gap cost roughly 15% of the returns their own funds generated.
The primary role of a good financial planner is to close that gap. To keep you invested during a crash. To talk you out of chasing last year's best-performing fund. To help you hold your nerve when the news is alarming. Vanguard's UK research on Adviser's Alpha estimates that advisers following best practices can add around 3% in net annual returns - and the single largest contributor is behavioural coaching.
But coaching only works when you trust the person giving it. And trust comes more easily when your planner has no hidden reason to steer you one way or another.
A fixed-fee planner who tells you to pay off your mortgage isn't reducing their own income. One who encourages you to gift money to your grandchildren isn't shrinking their fee base. The advice is clean.
Robert describes the investment philosophy behind it: "By investing based on what evidence shows works, you give the client the highest likelihood of achieving their objectives. You keep costs low. When costs aren't being paid to unnecessary fund managers, more wealth stays in the client's portfolio to grow. That's the power of compounding."
Compounding works both ways. Lower costs compound in your favour. Poor decisions compound against you. Good advice, delivered without conflicts of interest, addresses both at once.
The emotional benefits matter too. Vanguard's 2025 survey of more than 12,000 investors found that 86% of advised clients reported greater peace of mind compared to managing their finances alone. Advised investors were roughly half as likely to suffer high financial stress. When you know your planner's advice isn't influenced by their own revenue, the confidence that follows is real.
What the experience actually feels like
Working with a fixed-fee planner feels different from the very first meeting. The conversation starts with your life, not your portfolio.
What does a fulfilling retirement look like to you? When do you want the option to stop working? What would you do with your time? What keeps you up at night? These aren't warm-up questions. They're the foundation of everything that follows.
No sensible architect draws plans before understanding how you live in your home. A financial planner shouldn't build a strategy before understanding what your money is actually for.
This approach regularly uncovers things clients hadn't considered. Robert puts it well: "What I love most about financial planning is helping people see what's enough. Knowing what is enough - that's one of the greatest forms of wealth. Once you understand that, you can make powerful decisions. Retire early. Change career. Step back to care for a loved one."
Many people have accumulated pensions, ISAs, and investment accounts over decades, but nobody has ever helped them connect those numbers to their actual life. "A lot of people don't realise they'd benefit from financial coaching," Robert adds. "Not just investment management, but truly understanding their relationship with money and how their choices could be improved."
The ongoing relationship reflects this philosophy. Rather than a single annual review where you run through a pack of slides, you have a planner who knows your situation and is available when life changes - an inheritance, a redundancy, a health concern, a new grandchild. The fee covers the relationship. Not a transaction.
How to find the right fixed-fee planner
Fixed-fee planners are still the minority in the UK, but they're growing in number. Here's how to identify the genuine article.
Ask one direct question first: "How do you charge?" If the answer involves a percentage of assets under management, you're looking at the traditional model. If it's a pound figure based on the work required, you're in the right territory. But go further - some firms call themselves "fixed fee" while still linking ongoing charges to portfolio size. Ask: "Will my fee increase if my investments grow?"
Understand what's included. A transparent planner will explain each stage separately - initial advice, implementation, ongoing service - and tell you exactly what's covered. Vagueness at this stage is a warning sign.
Notice where the conversation starts. A planner focused on your goals will ask about your life before your money. One focused on gathering assets will want to know your portfolio size within the first few minutes. The difference is unmistakable once you're looking for it.
Trust your instincts. You're hiring someone to guide decisions that will shape your retirement, your family's security, and your peace of mind. If the relationship doesn't feel right, it probably isn't.
The standard you'd expect from any professional
You wouldn't pay your solicitor more because your house went up in value. You wouldn't accept an accountant whose fees climbed every time your savings grew. You'd expect to pay for expertise, for time, for professional judgement applied to your specific situation.
Financial advice should work the same way.
A fixed-fee financial planner charges for what they do, not what you own. That single change aligns their interests with yours, removes the quiet drag of compounding percentage fees, and makes space for advice that genuinely serves your goals rather than someone else's revenue target.
rockwealth Chiswick offers a free initial discovery consultation - no obligation, no pressure. Just a conversation about what you want from your financial life, and whether we can help you get there.
The way you pay for advice shapes the advice you receive. Choose accordingly.